Key Points:
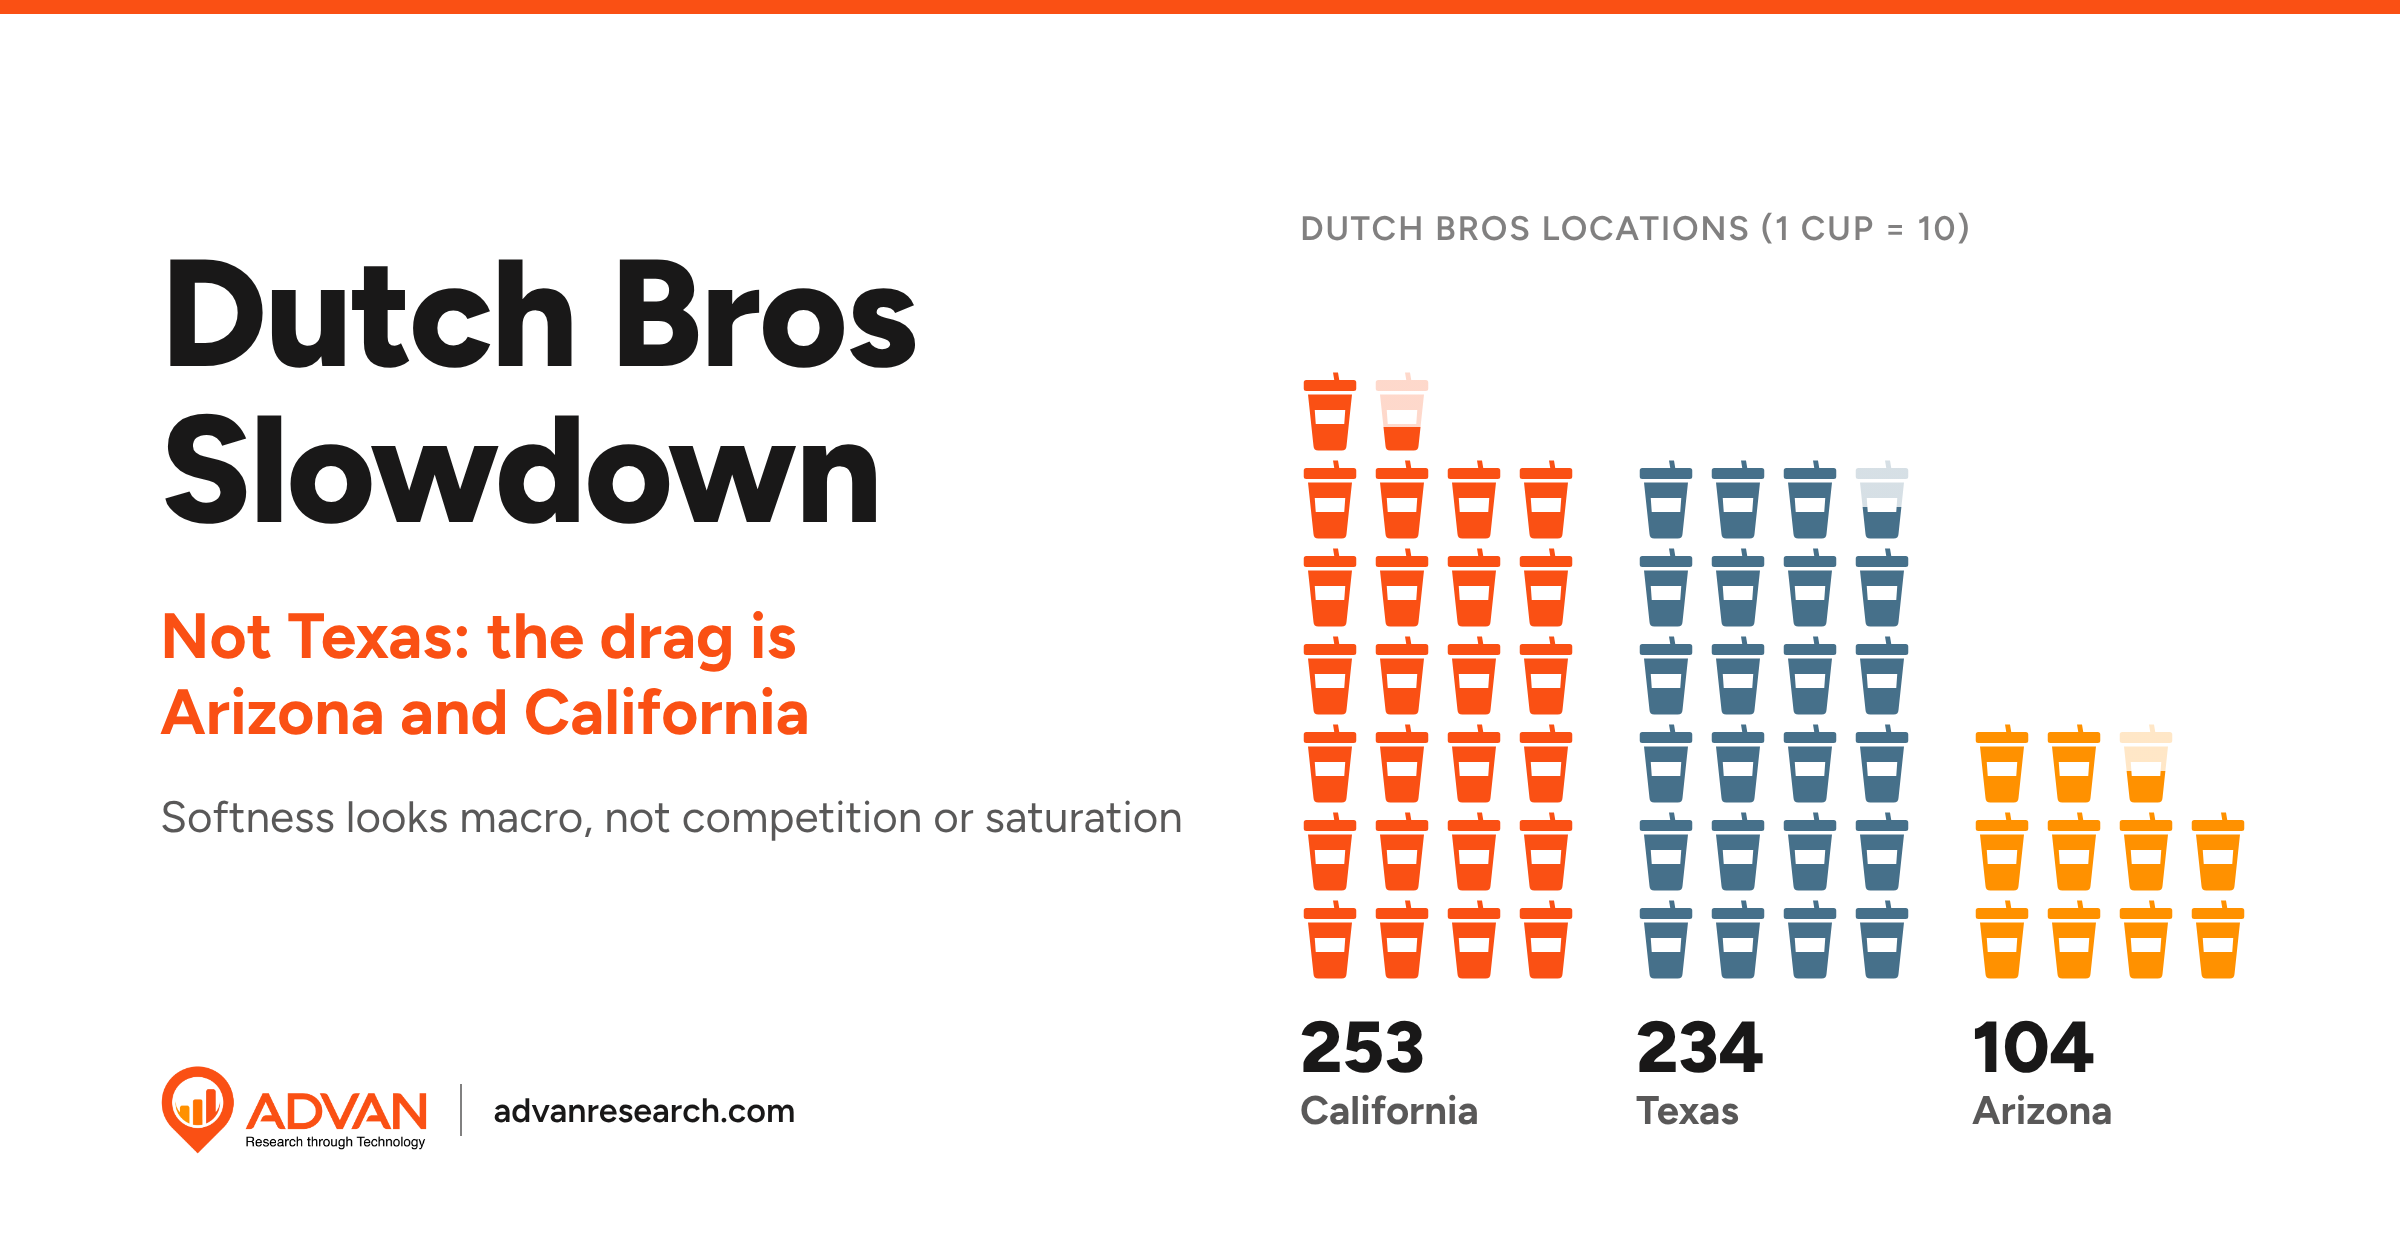
- The slowdown in BROS sales wasn’t in Texas, as is widely speculated; the drag is Arizona and California. California is now a larger market store-wise (253 locations) than Texas (234).
- Over the past year, California has seen 40 new locations. Arizona (104) is half store-wise, but per pop, Arizona is twice Texas and California at 13.6 locations per million residents.
- Management’s guidance implies flat-to-down comp-traffic for Q4, down from the reported Q3 figure of +0.4%.
- Two weeks ago, Starbucks reported very strong CQ3 results, including US comp-traffic of +2.7%.
- The observed comp-traffic for Starbucks was slightly stronger QoQ in California and slightly weaker QoQ in Arizona. However, October was a 2 percentage point drop in both markets. As such, we agree with BROS management that the softness is “macro” vs. competition (7 Brew, SBUX, MCD, etc.) or saturation (i.e. overbuilding in California or Texas).
- On a nationwide basis, the rise in gas prices has impacted gallons pumped (EIA data), which will result in fewer miles driven. That in turn, leads to fewer drive-bys past Dutch Bros kiosks. We’ve also previously shared that the midterms were a damper on consumer activity. The midterms have now passed.