- The US consumer came in as remarkable with October Retail Sales (per the Census Bureau) once again strong and despite the midterm election campaign gloom. Catching our eye was non-store retailers (+11.8% YoY), which is above the +10.4% trend; that strengthening reflects solid results for Amazon’s Prime Big Day Deals (October 6-7th). Also catching our eye was miscellaneous retailers (+13.3%), and that was strength from secondhand retailers. Secondhand had a very strong October given that Halloween fell on a Saturday, leading to more Halloween parties this year; secondhand is where many consumers go to score their Halloween costumes, especially Gen Z and Millennials.

- Secondhand fashion’s strength is not just Halloween. Secondhand has been producing very strong YoY growth since early-2025. It’s in a supercycle that’s driven by not only overall consumer thriftiness, but also the retro, authenticity, individuality, and fast-fashion-rebellion / sustainability trends. The secondhand strength is sizable with YTD $-growth reaching 25% of the $-growth of apparel stores (i.e. new clothes). And that’s just bricks & mortar; eBay and Poshmark “secondhand” US businesses are growing over 20%. Below, we share two slides from eBay’s Recommerce Report; the statistic that struck me is that 53% of 18- 29-year-olds expect to buy more secondhand, implying that over 50% already do. (My 25-year-old son only buys secondhand.)
- Apparel also continues its supercycle fueled by wardrobe upgrades. Driving the upgrades are smaller bodies (GLP-1 drugs), back-to-office five days per week (more outfits), and the classy-dressy (from athleisure) trend. (See our story on Lululemon’s woes.) As shown in the chart, the retail category has grown mid- to high-single-digits each month since 2024. Pre-pandemic, its growth CAGR was less than 1%; that’s a supercycle lift.
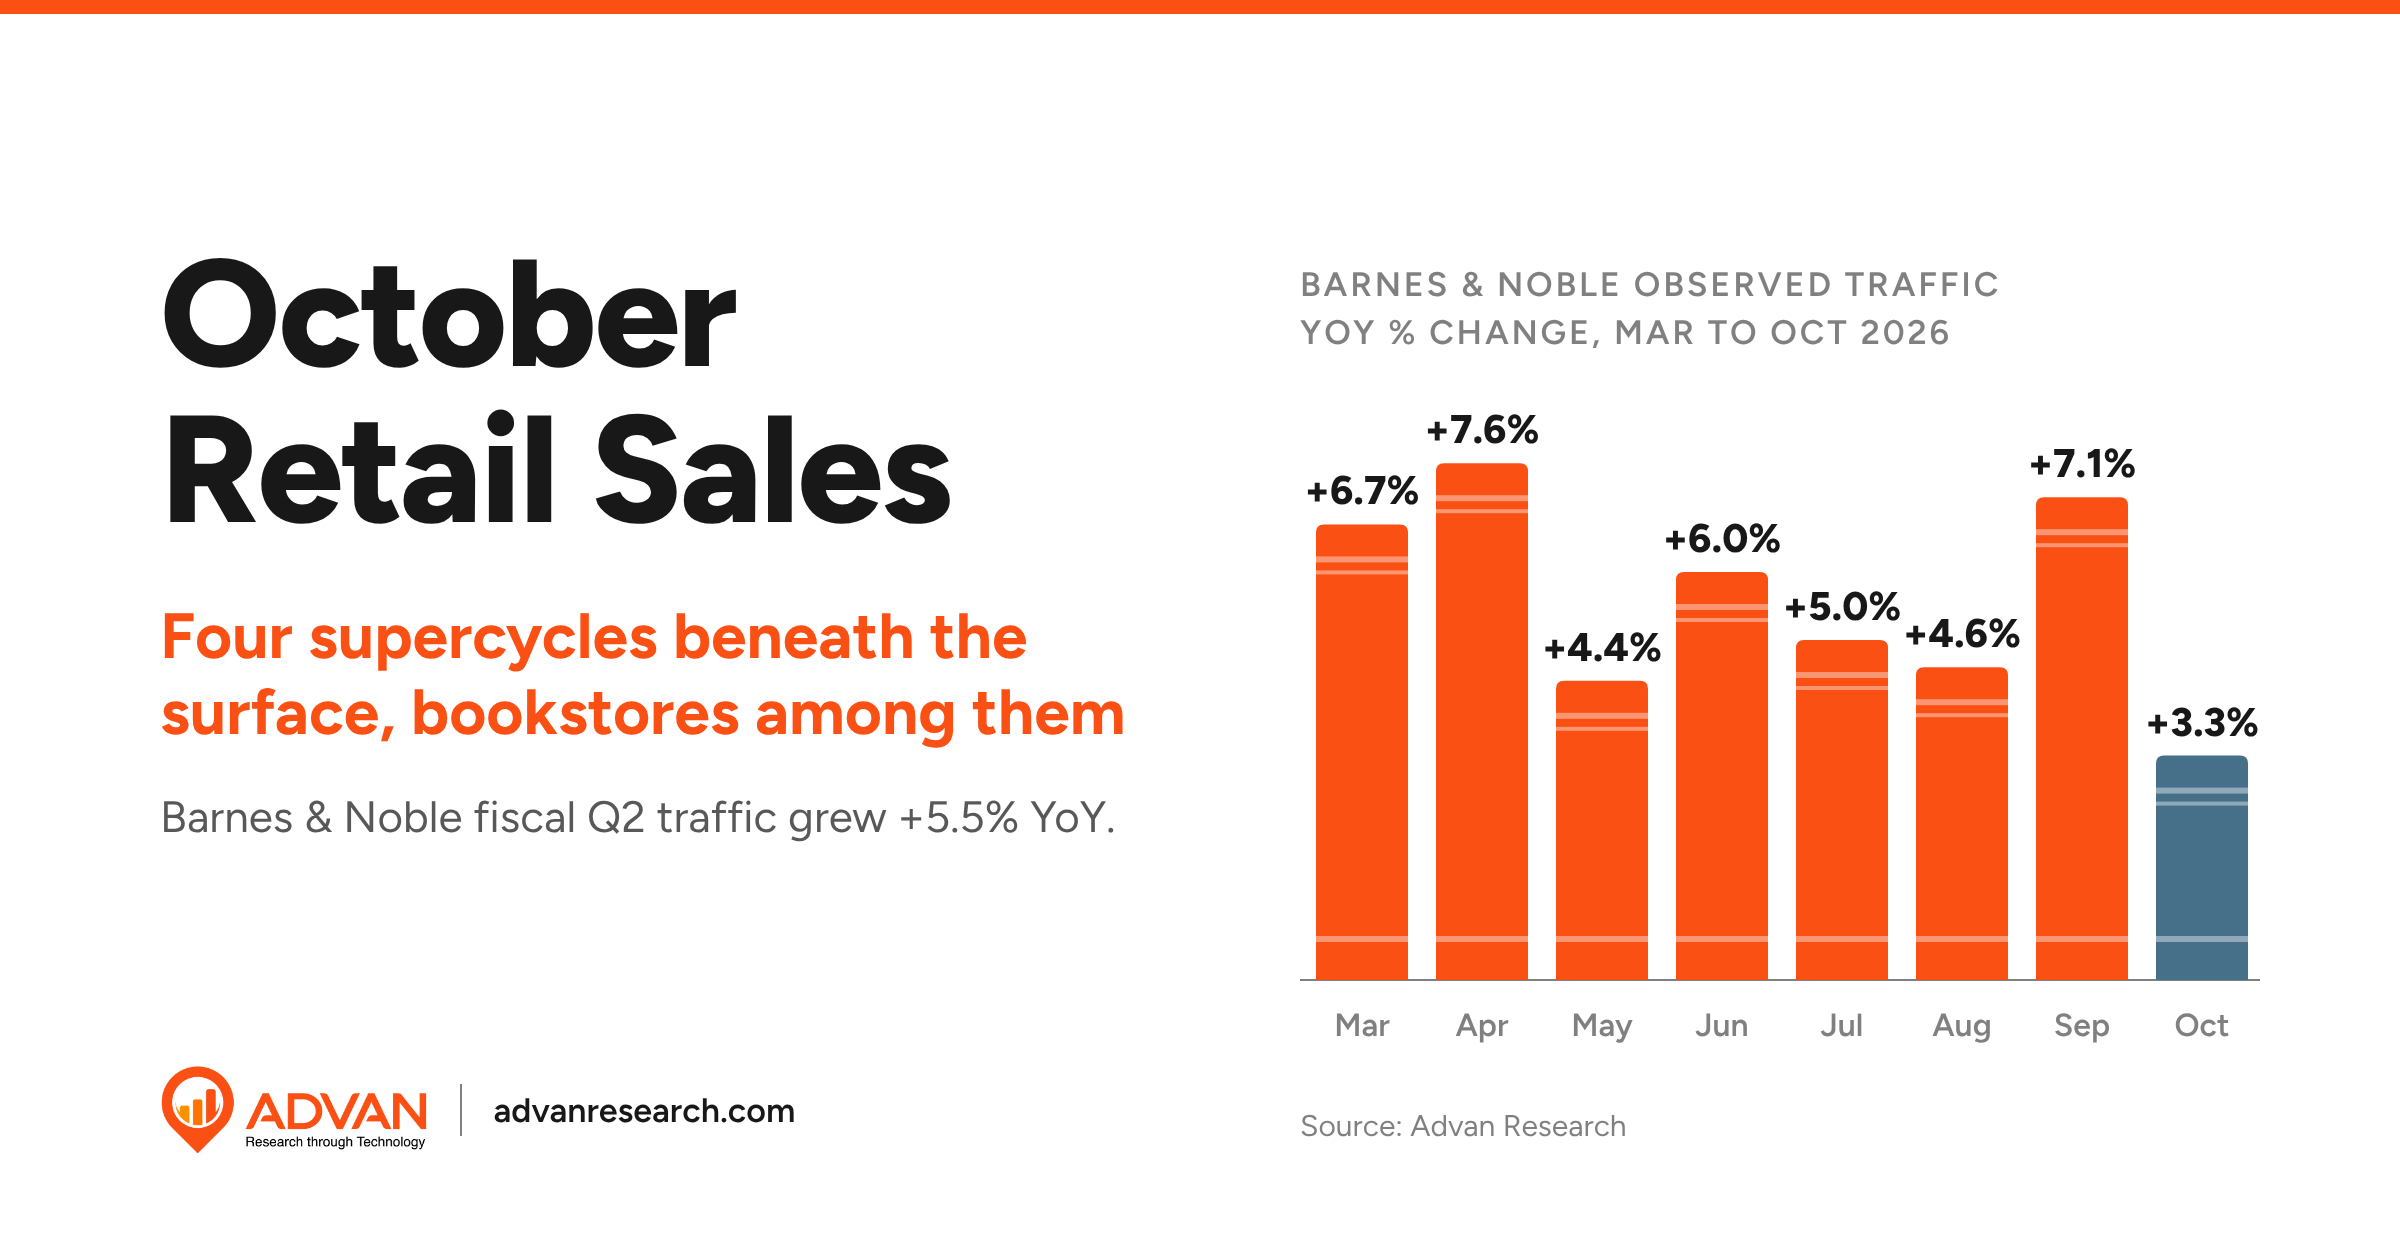
- Bookstores continue to outperform (yes, you read that right, bookstores) and are also in a supercycle. The new book releases in August were a blow-out success, with brick-and-mortar sales increasing +31%. Barnes & Noble has been putting up very impressive traffic and sales growth since 2024. Below, we show observed traffic to its locations on a quarterly and monthly basis. (Give us a call to demo our new portal for investment-finance users.) As Starbucks has done, bookstores have reclaimed their role as a 3rd place in people's busy lives. They are safe and quiet places of human curation, human mingling, and sensory (that new book texture and smell).

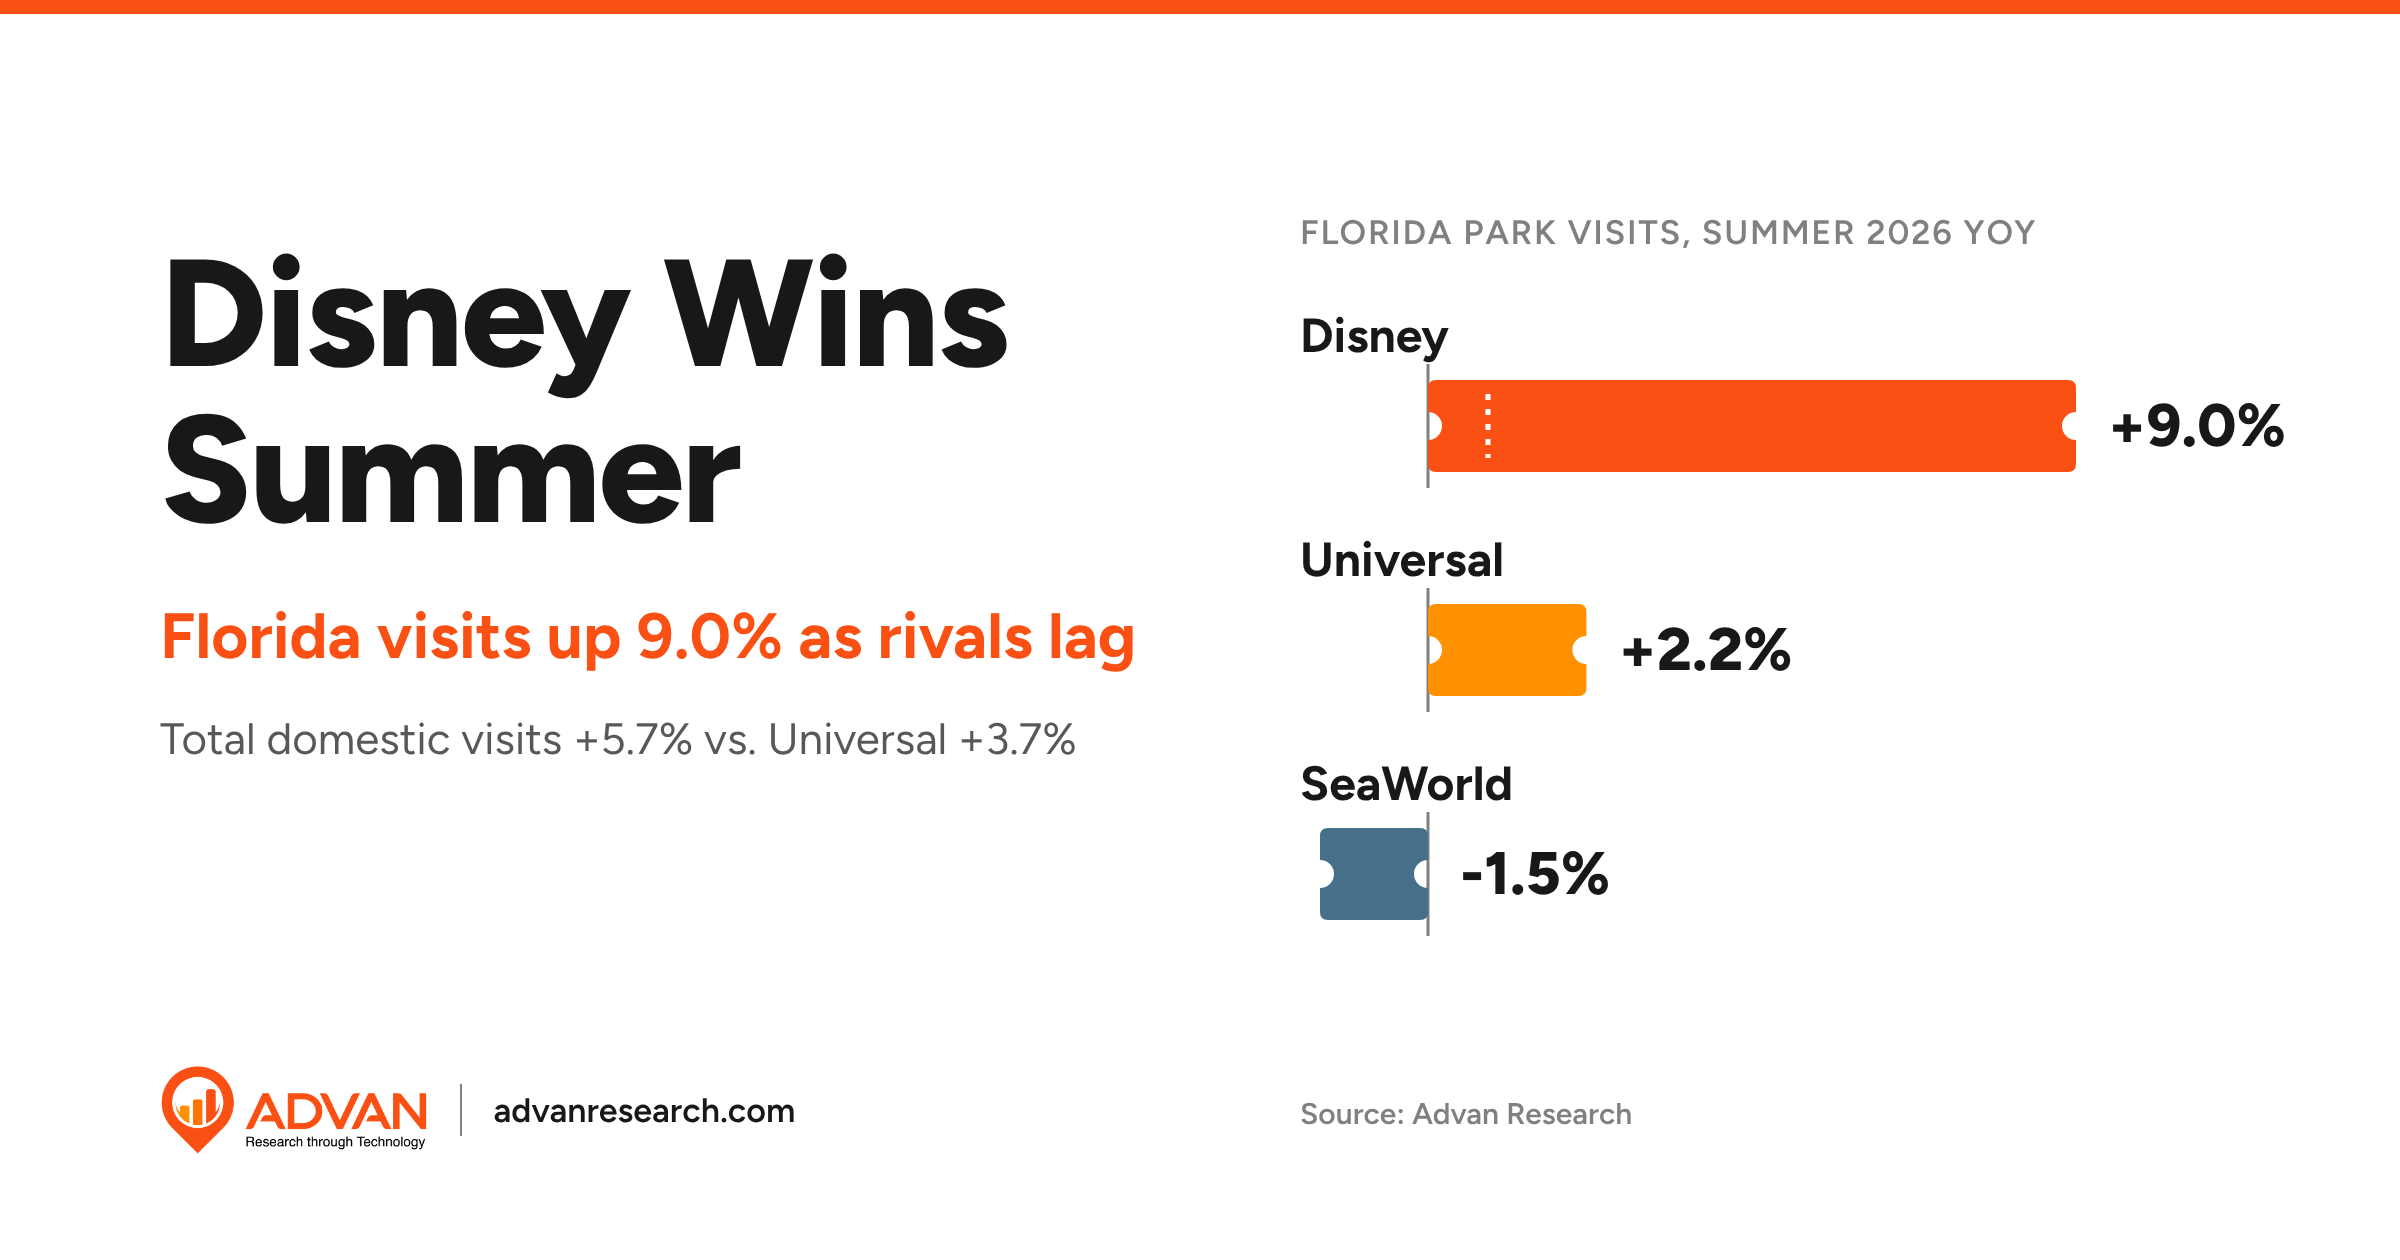
- Game and toy stores continue to produce outlandish YoY growth. That’s adults being kids and using their adult-sized wallets to buy trading cards and other collectibles. And it’s not just at brick-and-mortar; collectibles is driving eBay’s US growth at a high-twenties rate. (The trend at eBay began to pick up in Q2’24, i.e. we’re two years into the rage.) Another example of adults playing kids is that 40% of Lego’s US sales are now to “Adult Kids.” (See here and here.) Yes, Five Below is going to report explosive comp-sales again, something in the +17% range. +17% would lift the business to +35% above its 2024 level on a comp basis. 35% is above Q2’26’s +21% lift from 2024 an acceleration that demonstrates that the collectibles supercycle is still gaining momentum! Just wait for its Holiday results. (Mattel? – no comment. Disney – they caught the cycle at its parks.)
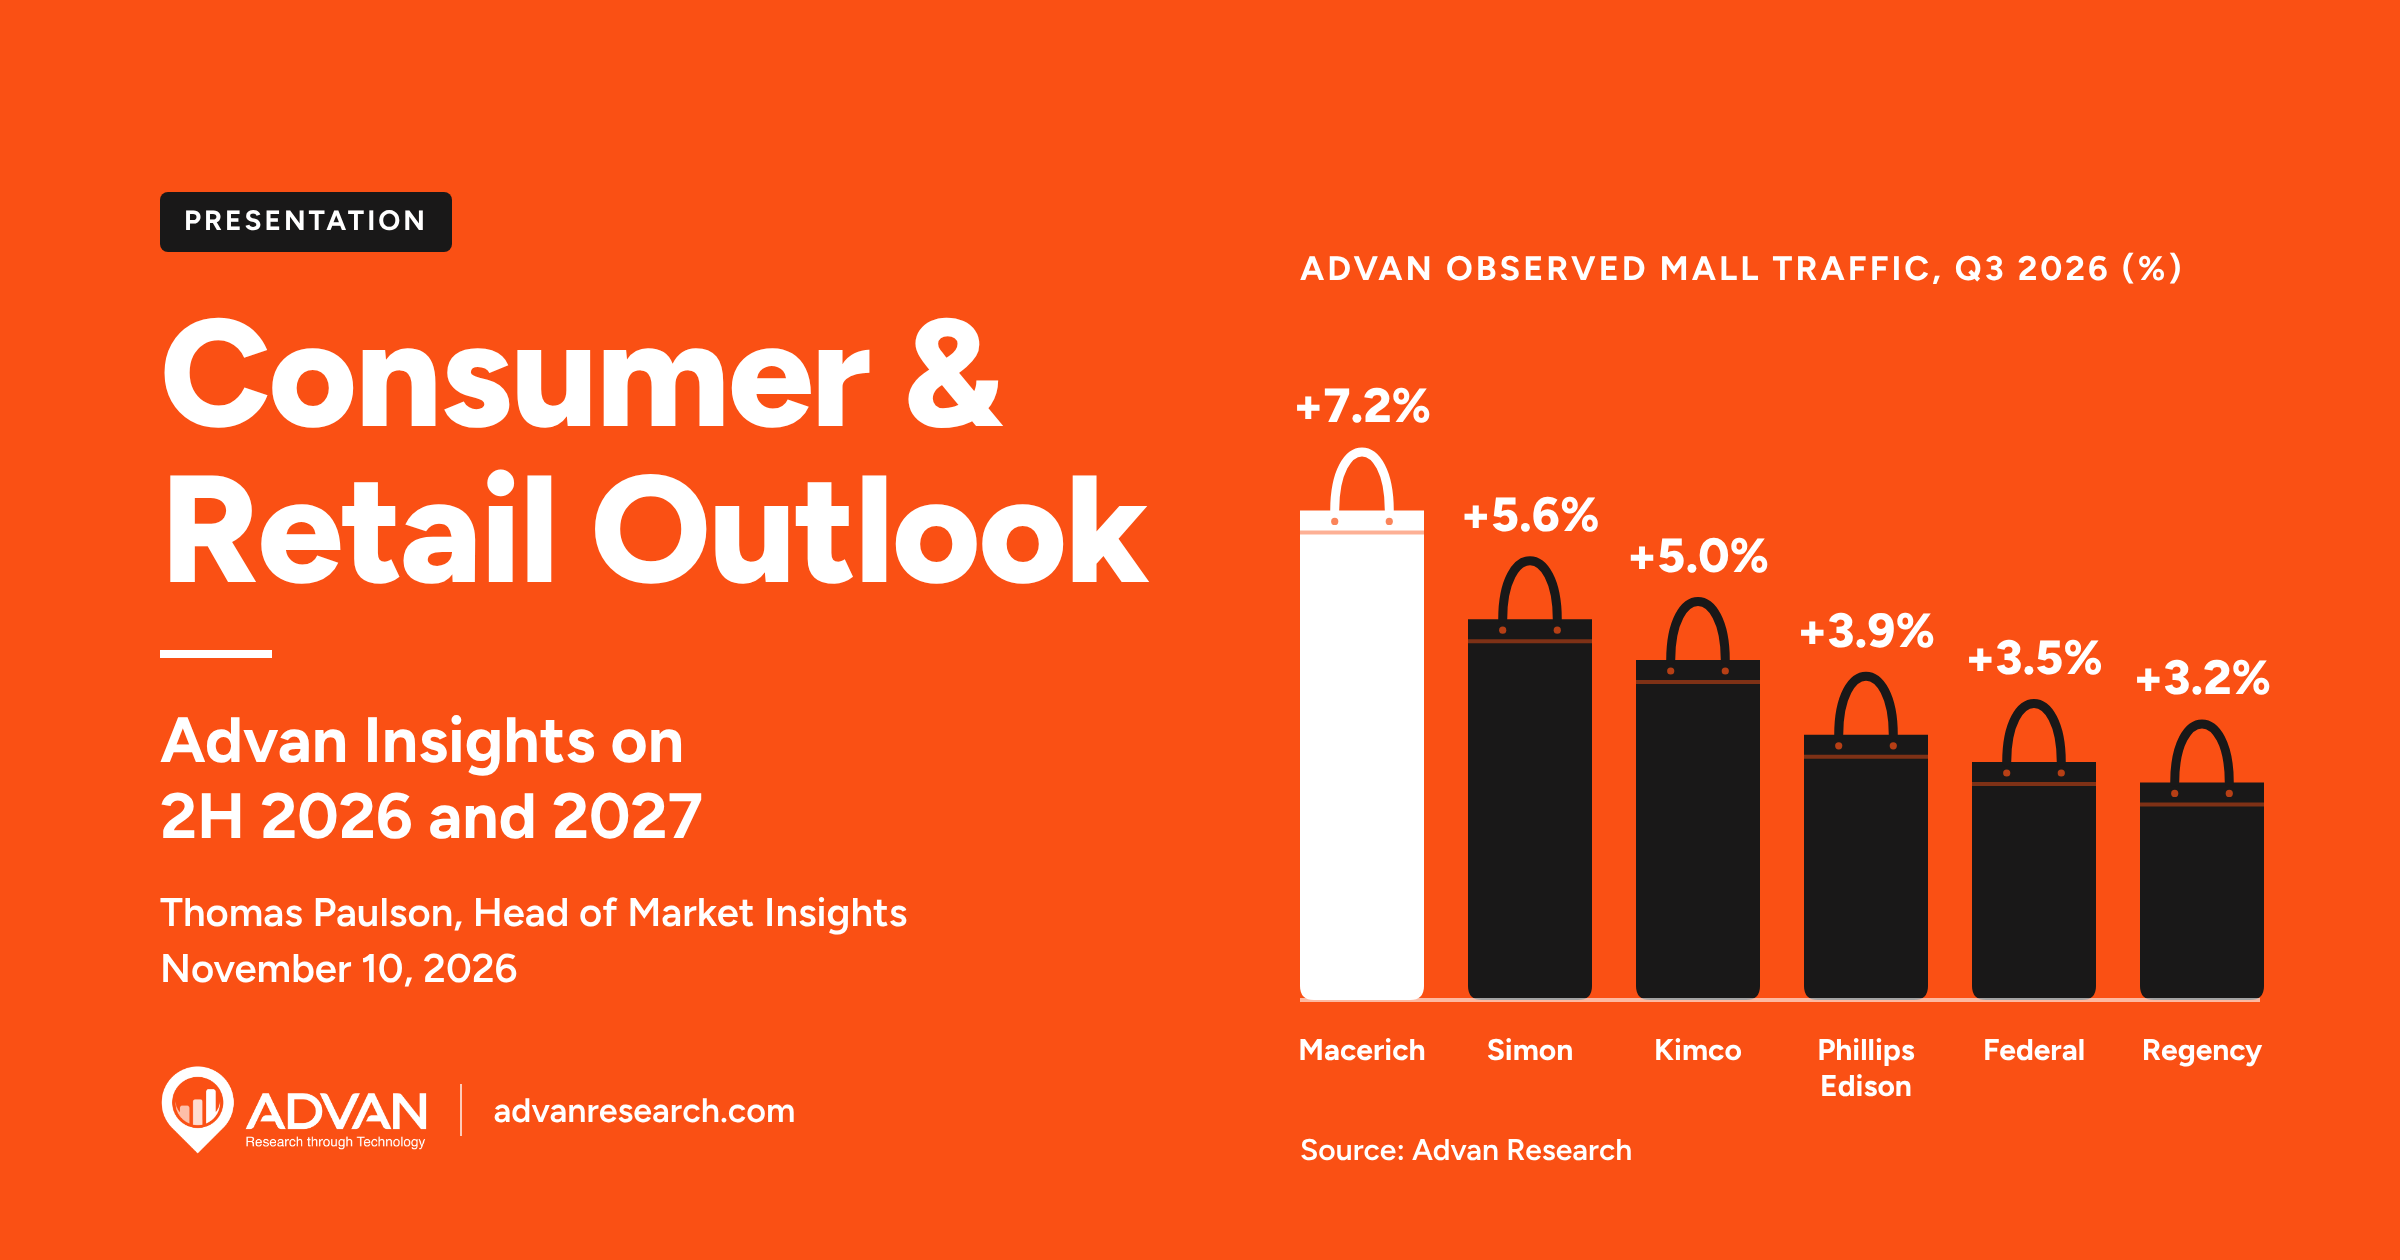
- Speaking of the Holiday and 2027, see our outlook presentation here. We expect a strong Holiday 2026, a more subdued 1H’27, followed by improving momentum in the 2H’27.